
Tax treatment of cryptocurrency varies by country, reflecting divergent classifications—property, currency, or financial asset. Gains, income, and reporting rules depend on jurisdictional definitions and tax policy aims. Special cases such as mining, staking, and airdrops further complicate timing and taxability, while fungible versus non-fungible assets introduce additional nuance. Cross-border activity demands meticulous record-keeping and compliant disclosures, creating a landscape where planning and auditable documentation matter, yet the path remains complex and unsettled.
Crypto Tax Classifications: Property, Currency, or Asset
Tax treatment of cryptocurrency varies by jurisdiction, but many countries categorize digital assets as property, capital assets, or monetary instruments for tax purposes. The Classification debate reflects divergent interpretations of how gains are taxed and when transfers occur. Jurisdiction definitions shape thresholds, exemptions, and reporting standards, influencing investors’ strategic decisions and cross-border flexibility in a global market.
Tax Treatment by Jurisdiction: Gains, Income, and Reporting
Across jurisdictions, the treatment of gains, income, and reporting obligations for cryptocurrency hinges on local definitions of taxable events and the preferred tax base. Jurisdictions diverge on whether gains are capital or ordinary income, how losses offset, and filing timelines. Crypto compliance and tax planning require coordinated records, transparent disclosures, and proactive planning to optimize liability and compliance outcomes globally.
Special Cases: Mining, Staking, Airdrops, and Fungible vs. Non-Fungible Assets
Special cases such as mining, staking, airdrops, and distinctions between fungible and non-fungible assets introduce nuanced tax considerations that can diverge across jurisdictions.
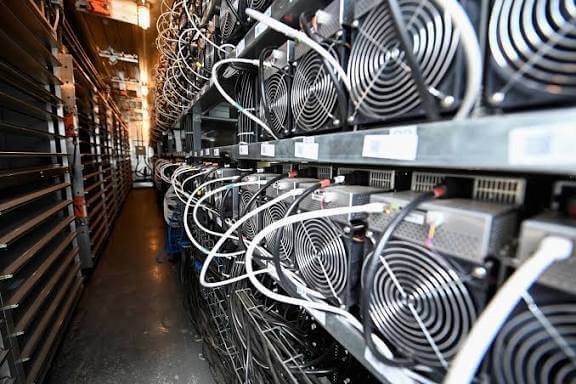
Jurisdictions typically treat mining incentives as ordinary income or self-employment income, while staking rewards may be taxed as income or capital gains.
Airdrops and asset classification influence timing and basis, guiding compliant, globally minded taxpayers seeking freedom.
Practical Cross-Border Compliance: Step-by-Step Reporting and Records
Coordinating cross-border cryptocurrency reporting requires a disciplined, step-by-step approach that aligns with each jurisdiction’s rules while preserving global consistency. The process emphasizes accurate transaction catalogs, documentation, and timely disclosures, balancing regulatory compliance with financial autonomy. Tax privacy considerations shape data minimization and secure sharing, while compliance automation reduces manual error, accelerates filings, and supports transparent, auditable records across borders.
See also: Exploring the Future of Web3 and Digital Communities
Conclusion
Tax treatment of crypto varies by jurisdiction, reflecting its evolving classifications as property, currency, or asset. Gains, income, and reporting rules differ widely, with special rules for mining, staking, airdrops, and the fungible versus non-fungible landscape. Cross-border activity requires meticulous record-keeping, timely filings, and coordinated disclosure to auditors and authorities. In this global patchwork, preparation pays: “Measure twice, cut once.” A disciplined approach ensures compliant, transparent, and efficient tax outcomes across borders.